


Industry Trends
Largest Transactions Closed
- Target
- Buyer
- Value($mm)
Advised Western Milling in their sale to the Western Milling ESOP Trust
Last updated:
Buyers remained active in Q3 2026, but focused their capital on scaled platforms, premium experiences, and businesses with defensible customer relationships or clear operating advantages. Strategic acquirers continued to lead activity, while sponsors pursued assets with identifiable opportunities to expand margins, accelerate growth, and build portfolios. Overall transaction volume declined year over year, and lower median valuation multiples reflected disciplined underwriting amid uneven discretionary demand. Notable deals spanned bedding products, restaurants, hospitality, automotive services, specialty retail, dealerships, and professional training.1
According to Joe Anto, Managing Director at PCE, “Consumer & Retail M&A remained active in Q3, particularly for differentiated businesses. Buyers are prepared to move quickly when they see durable demand, strong customer relationships, and a clear path to creating value. At the same time, they remain disciplined when earnings are less predictable or the strategic fit is unclear.”
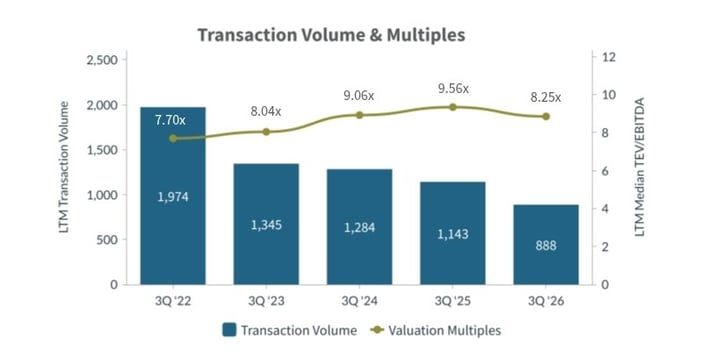
Deals totaled 888 on an LTM basis, down from 1,143 a year earlier, as activity remained below prior-year levels. Median valuation multiples also declined, with EBITDA multiples decreasing to 8.25x from 9.56x and revenue multiples decreasing to 1.28x from 1.54x. The combination of lower volume and lower pricing indicates a selective market in which buyers favored scaled, differentiated assets and applied greater scrutiny to discretionary exposure, margin durability, and post-close execution.1
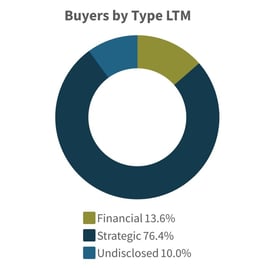
Strategic Acquirers: Strategic buyers represented 78.2% of the 863 LTM transactions for which buyer type was identified, accounting for 675 deals. The remaining classified transactions included financial sponsors and other buyer types.1
Financial Buyers: Financial sponsors accounted for 11.5% of classified LTM deals—99 of the 863 transactions for which buyer type was identified—selectively deploying capital into platforms and assets with repeatable revenue, pricing power, and operational improvement potential. Lower entry multiples created opportunities, but financing costs, valuation gaps, and uneven consumer demand continued to shape underwriting.1
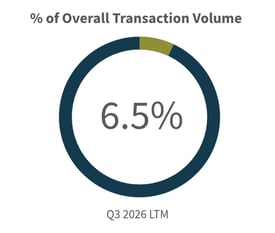
Consumer & Retail dealmaking in Q3 2026 continued to reflect a K-shaped market: transaction volume and valuation multiples were lower, but capital remained available for larger, differentiated assets with strategic relevance and credible value-creation plans. Broader market commentary similarly emphasized operating advantage, resilient demand, customer ownership, and execution visibility as key drivers of buyer conviction.1 2
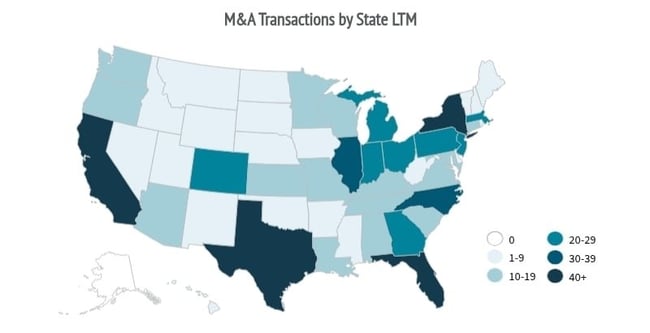
Top U.S. States: Florida led LTM deal activity with 91 transactions, followed by California with 85 and Texas with 80. These states represented the highest transaction counts in the dataset.1
Cross-Border Trends: Q3 activity remained primarily domestic, although select international capital continued to pursue U.S. hospitality and leisure assets where premium positioning, loyalty, and customer data supported conviction.1 3
| Target | Buyer | Value |
| Leggett & Platt, Incorporated | Somnigroup International Inc. | $3,255.00 |
| Pizza Hut, LLC | LongRange Capital, L.P. | $1.575.00 |
| JW Marriott Orlando Grande Lakes Resort/Ritz-Carlton Orlando, Grande Lakes/Certain related assets | Ryman Hospitality Properties, Inc. | $1,380.00 |
| The Pep Boys-Manny, Moe & Jack LLC | Mavis Tire Express Services Corp. | $700.00 |
| Hot Topic Inc. | Spencer Spirit Holdings, Inc. | $350.00 |
| Hyatt Regency San Francisco | Blackstone Real Estate Advisors L.P. | $279.00 |
| Pier House Resort & Spa | Sixth Street Partners, LLC | $190.00 |
| Pier House Resort & Spa | Last Mango Owner LLC | $184.60 |
| The Container Store, Inc. | Neighborhood Intelligence, Inc. | $176.50 |
| Arlington Hotel Operator, L.L.C. | Columbia Sussex Corporation | $92.30 |
| Target | Buyer | Value |
| Hilton Garden Inn Louisville Mall of St. Matthews | Spark GHC | $25.00 |
| Target | Buyer | Value |
| Fremont Marriott Silicon Valley | SRE Acquisitions | $52.20 |
| Holman Honda Of Fort Lauderdale | Len Stoler, Inc. | $44.80 |
| DURA Automotive Systems, LLC | Aspire-Lakewood Holdings, Inc. | $30.00 |
| Kizuki International LLC | Yoshinoya Holdings Co., Ltd. | $21.20 |
| Global Knowledge Training LLC | EHJob GP LLC | $20.00 |
Source S&P Capital IQ as of 10/2/2026 and PCE Proprietary Data
Opportunities: Q4 activity may benefit from portfolio reviews, sponsor exit pressure, and strategic demand for differentiated consumer assets, premium experiences, functional nutrition, digital capabilities, and businesses with strong customer ownership.2 3 4
Risks: Financing costs, tariff and geopolitical volatility, persistent valuation gaps, integration complexity, and uneven discretionary spending may continue to lengthen diligence and constrain activity for less differentiated businesses.2 3
Predicted Activity: Based on current transaction trends and cited market commentary, Q4 dealmaking may remain measured but active, with strategic buyers likely to lead volume and sponsors concentrating on platforms and add-ons where durable demand, pricing power, operating leverage, and clear post-close execution support conviction.1 2

Joe Anto |
Eric Zaleski |
Kyle Wishing |
Advised Western Milling in their sale to the Western Milling ESOP Trust
