


Industry Trends
Largest Transactions Closed
- Target
- Buyer
- Value($mm)
Advised Western Milling in their sale to the Western Milling ESOP Trust

Last updated:
Banking, Finance, and Insurance M&A remained active but increasingly concentrated in Q3 2026. Trailing-twelve-month transaction volume declined to 589 from 689 a year earlier, while strategic acquirers represented 97.2% of classified transactions. The quarter was defined by large insurance brokerage and regional-bank combinations, and execution certainty.1 2
“Q3 reflected a concentrated FIG M&A market in which fewer transactions were offset by several transformational combinations,” said David Jasmund, Managing Director at PCE. “Strategic buyers continued to prioritize scale, defensible customer relationships, strong deposit and distribution franchises, and technology-enabled capabilities, while financial sponsors remained highly selective.”
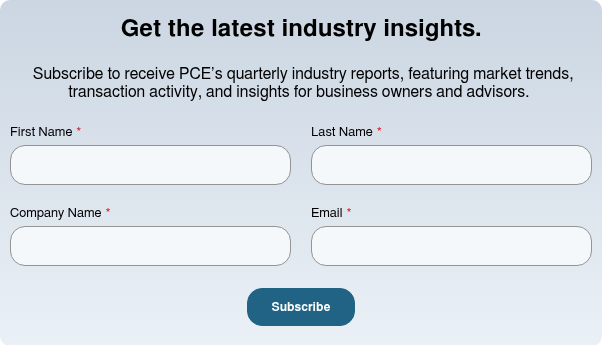
In Q3 2026, Banking, Finance, and Insurance M&A volume declined to 589 transactions for the trailing twelve months from 689 in Q3 2025, a decrease of approximately 14.5%. Median TEV/Revenue declined to 1.36x from 1.47x, while median TEV/EBITDA fell to 8.58x from 10.05x. Median Price/Book Value increased to 1.47x from 1.37x, while median Price/Earnings declined to 11.99x from 13.10x, indicating continued selectivity and a premium for balance-sheet quality, scale, and strategic fit.1
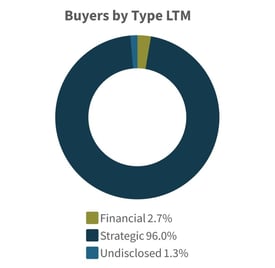
Strategic Acquirers: Strategic buyers accounted for 97.2% of classified trailing-twelve-month transactions. Activity was led by insurance brokerage consolidation and regional-bank combinations, with acquirers using M&A to add scale, deepen market density, expand distribution, and acquire technology or specialized capabilities.1 4
Financial Buyers: Financial buyers represented 2.8% of classified trailing-twelve-month deal volume. Sponsor activity remained limited relative to strategic activity and focused on opportunities with recurring revenue, scalable platforms, and capital-efficient structures, including minority investments, reinsurance vehicles, and other partnership models.1 3
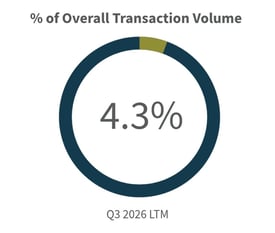
Banking, Finance, and Insurance represented approximately 26% of the 2,274 U.S. transactions captured across the broader Q3 2026 market data. Although sector volume declined year over year, large insurance brokerage and banking combinations kept disclosed value concentrated in a small number of strategic transactions, consistent with the broader market’s emphasis on scale and capability-led M&A.1 2 4
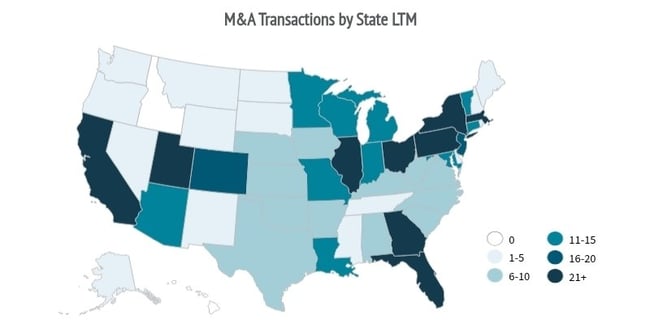
Top U.S. States: California led with 35 transactions, followed by Illinois with 34 and Florida with 33, reflecting continued concentration in large financial-services markets and states with substantial banking, insurance, and specialty-finance ecosystems.1
Cross-Border Trends: Q3 activity remained predominantly domestic, although cross-border financial-services transactions continued where buyers could add scale or differentiated capabilities. Broader market evidence points to a multi-speed recovery, with North America leading activity while geopolitical uncertainty and financing conditions continued to make execution more selective.2 6
| Target | Buyer | Value |
| Webster Financial Corporation | Santander Holdings USA, Inc. | $12,222.24 |
| Stellar Bancorp, Inc. | Prosperity Bancshares, Inc. | $1,,998.98 |
| Northfield Bancorp, Inc. | Columbia Financial, Inc. | $596.61 |
| Signature Bancorporation, Inc. | Esquire Financial Holdings, Inc. | $393.02 |
| OFB Bancshares, Inc. | Hancock Whitney Corporation | $377.60 |
| Everett Cash Mutual Insurance Company | Old Republic International Corporation | $207.00 |
| Pacific Financial Corporation | Banner Corporation | $177.44 |
| Affinity Bancshares, Inc. | The Fidelity Bank | $147.97 |
| Peach State Bancshares, Inc. | United Community Banks, Inc. | $101.05 |
| Adirondack Bancorp, Inc. | Arrow Financial Corporation | $89.93 |
| Target | Buyer | Value |
| Hancock Claims Consultants Holdings, LLC | Cornell Capital LLC | n/a |
| Strategic Funding Source, Inc. | InterVest Capital Partners LLC | n/a |
| Lovell Insurance Group, LLC | Creative Planning, LLC | n/a |
| Target | Buyer | Value |
| Farmers Bancorp | Richmond Mutual Bancorporation, Inc. | $85.72 |
| HCB Financial Corp. | Independent Bank Corporation | $70.19 |
| TruSpire Retirement Insurance Company | Malibu Life Reinsurance SPC | $45.00 |
| Lakeside Bancshares, Inc. | Catalyst Bancorp, Inc. | $41.08 |
| Pacific West Bancorp | FS Bancorp, Inc. | $35.01 |
Source S&P Capital IQ as of 10/1/2026 and PCE Proprietary Data
Opportunities: Regulatory tailwinds, excess capital, and continued pressure to fund technology should support additional bank consolidation and capability acquisitions. Insurance brokerage, specialty insurance, payments, and wealth-management platforms with defensible earnings and scalable infrastructure should remain attractive.2 4 5
Risks: Persistent inflation, geopolitical volatility, credit-quality concerns, valuation gaps, and integration complexity remain the principal risks to execution. The decline in sector volume and valuation multiples also suggests that smaller or less differentiated assets may face longer timelines and greater pricing pressure.1 2
Predicted Activity: Q4 activity is expected to remain strategic-led and concentrated in larger, high-conviction transactions. Bank combinations should emphasize deposits and market density, while insurance deals should favor distribution, specialty capabilities, and instances where private buyers see durable operating growth that is not reflected in public-market valuations. Fintech activity should center on payments, AI, and infrastructure.3 4 6 7
David Jasmund |
Michael Poole |
Kyle Wishing |
Advised Western Milling in their sale to the Western Milling ESOP Trust
