David Jasmund

E: djasmund@pcecompanies.com

Follow me: LinkedIn

Executive Summary


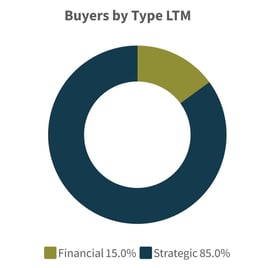
Aerospace, defense, and government contracting M&A remained active through the third quarter of 2026, supported by strategic demand for differentiated technology and mission-critical capabilities. Seventeen transactions closed during the quarter, bringing LTM volume to 140 deals. Strategic buyers represented 85% of LTM activity, while financial buyers accounted for 15%. LTM median valuation multiples were 18.49x TEV/EBITDA and 3.97x TEV/Revenue, compared with 18.76x and 3.99x, respectively, in Q3 2025.
 Get the latest industry insights. 

The quarter’s largest disclosed transactions were Ondas’ $829.9 million acquisition of DZYNE Technologies, Booz Allen Hamilton’s $720.0 million acquisition of Ultra Electronics Advanced Tactical Systems, and Iridium Communications’ $521.7 million acquisition of Aireon.¹³

“Companies that bring together national security, advanced manufacturing, and digital capabilities continue to stand out in the market,” said David Jasmund, Managing Director at PCE. “Buyers are looking beyond scale and focusing on capabilities that are difficult to replicate, especially when regulatory requirements, specialized expertise, and contract access create lasting competitive advantages.”

Market Dynamics


Although quarterly transaction volume moderated to 17 deals in Q3 2026, LTM activity remained substantial at 140 transactions. Valuations were also stable: median LTM multiples of 18.49x EBITDA and 3.97x revenue remained in line with Q3 2025 levels. This resilience reflects continued demand for differentiated aerospace and defense assets. Strategic acquirers pursued vertical integration, proprietary technology, and contract access, while financial sponsors concentrated on scalable platforms with recurring revenue, recompete visibility, and compliance readiness.13
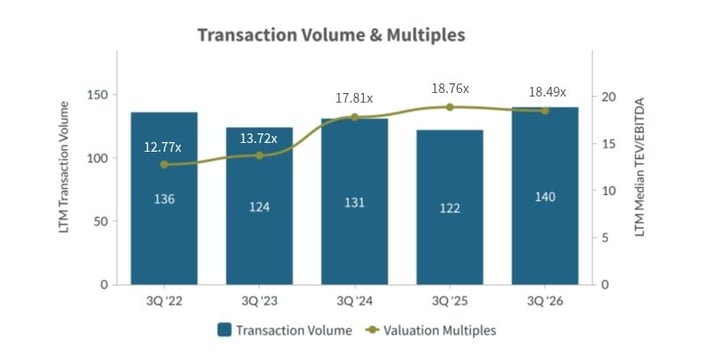
Q3-2026-Transaction Volume and Multiples Aerospace Defense Industry

Buyer Landscape


Q3-2026-Buyers by Type LTM Aerospace Defense Industry

Strategic Acquirers: 119 of 140 LTM transactions (85.0%) were completed by strategic buyers. Activity centered on defense technology, aerospace sustainment, autonomous systems, space infrastructure, electronics, and mission-support capabilities. Buyers continued to prioritize proprietary intellectual property, cleared workforces, established customer relationships, and vertical integration opportunities.13

Financial Buyers: 21 of 140 LTM transactions (15.0%) involved financial buyers. Sponsors remained selective, favoring aerospace components, MRO, government services, and defense-adjacent technology businesses with durable cash flow, contract renewal visibility, and mature cybersecurity and compliance infrastructure.13
Industry Comparison


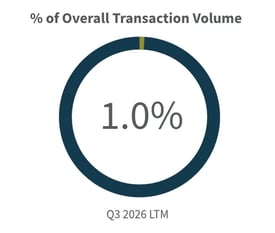
Q3-2026-Overall Transaction Volume Aerospace Defense Industry

Aerospace, Defense & Government Contracting accounted for a small but meaningful share of U.S. M&A activity. The sector represented 17 of 2,300 U.S. transactions in Q3 2026, or approximately 0.74% of quarterly volume, and 140 of 13,708 transactions on an LTM basis, or approximately 1.02% of total volume. Activity continued to benefit from long-term defense priorities, mission-critical customer relationships, aerospace aftermarket demand, and high barriers to entry created by regulation, security clearances, and technical requirements.13

Geographic Expansion


LTM seller activity was led by California (23), Florida (11), Texas (11), Virginia (9), Maryland (6), and New York (6). These markets benefited from established aerospace manufacturing clusters, defense installations, MRO capacity, federal customer proximity, and concentrations of cleared technical talent.13

California remained the most active state, supported by its established aerospace manufacturing base. Florida and Texas continued to generate aerospace manufacturing, aviation services, and MRO transaction activity, while Virginia and Maryland remained important centers for defense technology and government contracting.13
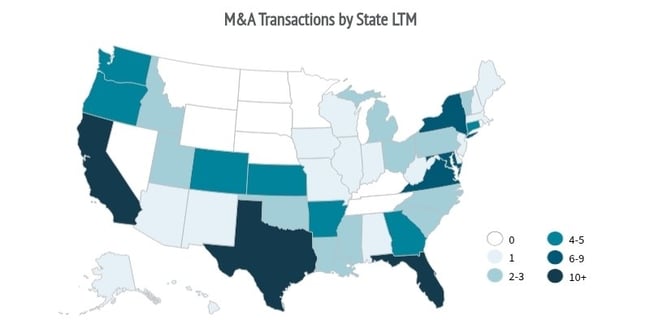
Q3-2026-MA Transactions by State Aerospace Defense Industry

Notable Transactions


Largest Transactions Closed

Target Buyer Value ($mm)
DZYNE Technologies, LLC Ondas Inc.  $830
Ultra Electronics Advanced Tactical Systems, Inc. Booz Allen Hamilton Inc. $720
Aireon LLC Iridium Communications Inc. $522
Astrobotic Technology, Inc. Voyager Technologies, Inc.  $300
Adaptive Dynamics, Inc. DTC Communications, Inc. $21

Other Financial Buyer Transactions Closed

Target Buyer Value ($mm)
Atlantic Aviation Corporation Apollo Global Management, Inc. n/a
TENICA Global Solutions McNally Capital, LLC; Nio Advisors, LLC n/a
Rhinestahl Corporation Capitol Meridian Partners LP n/a

Other Strategic Buyer Transactions Closed

Target Buyer Value ($mm)
Omega Aerial Refueling Services, Inc. Augustus Global LLC n/a
JCM Engineering Corp. High Tech Solutions LLC n/a
Collinear Group, LLC Capgemini Engineering S.A. n/a
Jet AirWerks, LLC Barnes Aerospace, Inc. n/a
Skyplace FBO Velocity FBO Network n/a
Atropos Group Inc. CHAOS Industries, Inc. n/a
Full Stop Technics LLC AvAir, LLC n/a
Iten Defense, LLC NP Aerospace Limited n/a
Sonatech, LLC Kongsberg Discovery AS n/a

Source S&P Capital IQ as of 10/1/2026 and PCE Proprietary Data

Emerging Trends


Key trends shaping Aerospace, Defense & Government M&A:

  1. Defense Modernization Drives Capital Deployment
    Spending priorities continue to favor autonomous systems, missile defense, electronic warfare, and next-generation command-and-control capabilities. Buyers are increasingly targeting differentiated technologies that support future-force modernization rather than traditional labor-intensive contracting models.8 11 12 15
  2. Space Becomes a Core Strategic M&A Vertical
    Commercial and defense space capabilities continue to attract investor interest as launch, satellite, communications, and ISR platforms become more integrated into national security infrastructure. Buyers are pursuing both established providers and emerging technology platforms across the evolving space economy.8 14
  3. Cybersecurity and Compliance Differentiate Winners
    CMMC readiness, zero-trust security, and AI-enabled cyber capabilities have become increasingly important competitive differentiators. Contractors with mature cybersecurity infrastructure, strong compliance processes, and established contract access remain attractive acquisition candidates.3 4 9
  4. Subsector Spotlight: Defense Technology, Autonomy & Space
    Investment activity remained concentrated in autonomous systems, AI-enabled mission platforms, missile defense technologies, and space infrastructure. The DZYNE, Ultra Electronics ATS, and Astrobotic transactions illustrate buyer appetite for assets aligned with unmanned systems, defense electronics, and space capabilities.12 14 15
  5. Subsector Spotlight: Aerospace Manufacturing & MRO
    Persistent OEM backlogs and supply-chain constraints continue to support aftermarket maintenance, repair, and overhaul demand. Buyers remain focused on certified manufacturers and MRO providers with recurring demand, specialized technical capabilities, and critical supply-chain positioning.5 6 7 12
  6. Subsector Spotlight: Cybersecurity, Federal IT & Government Services
    Federal agencies continue investing in cloud modernization, cyber resilience, AI adoption, and digital mission support. Contractors with prime contract access, strong past performance, compliance infrastructure, and recurring customer relationships remain well positioned for buyer interest.2 4 9

Outlook for Next Quarter


Deal activity is expected to remain active in Q4 2026, led by strategic consolidation across defense technology, aerospace services, and government contracting. Opportunities should remain strongest for companies with differentiated technology, mission-critical customer relationships, and exposure to autonomy, cybersecurity, space, and advanced manufacturing. Key risks include federal budgeting uncertainty, workforce constraints, evolving compliance requirements, limited contract diversification, and greater valuation scrutiny for subscale or less differentiated contractors.13
PCE Transactions


Grant Aviation


Served as advisor to Grant Aviation on their sale to Westward Partners

HopAJet

Served as advisor to Hop-A-Jet Worldwide Jet Charter as they became 100% ESOP owned

Unique Electronics

Served as advisor to Unique Electronics for senior debt refinancing

Williams Electric

Served as advisor to Williams Electric Co., Inc. on their sale to Parsons

Milcom

Served as advisor to Milcom Technologies for a fairness opinion

SEO

Served as advisor to Schwartz Electro-Optics, Inc. on their sale of Auto Sense to Osi Laserscan


Contact Us


jasmund-david-667x667

David Jasmund
Orlando Office
407-621-2111 |
Email me now

READ MORE →

rosendahl_michael-667x667

Michael Rosendahl
New York Office
201-444-6280 |
Email me now

READ MORE →

zaleski-eric-667x667

Eric Zaleski
Chicago Office
847-239-2466 |
Email me now

READ MORE →


Data Assumptions

This report represents transaction activity as mergers & acquisitions, consolidations, restructurings and spin-offs. Targets are defined as U.S. Based companies with either foreign or U.S. based buyers. Transaction information provided is based on closed dates only.

Glossary

EBIT - Earnings Before Interest and Taxes
EBITDA - Earnings Before Interest, Taxes, Depreciation, Amortization
LTM - Last Twelve Months
TEV - Total Enterprise Value

Sources:

  1. U.S. Department of Defense. “FY2027 Defense Budget Request and Supporting Materials,” 2026.
  2. Congressional Research Service (CRS). “Defense Primer: Unmanned Aircraft Systems and Autonomous Technologies,” 2026.
  3. Deltek GovWin. “Federal Government Contracting Market Outlook 2026,” Q3 2026.
  4. GAO. “Cybersecurity Maturity Model Certification (CMMC) Implementation Update,” 2026.
  5. Aerospace Industries Association (AIA). “2026 Facts & Figures: U.S. Aerospace and Defense Industry,” 2026.
  6. IATA. “Airline Industry Economic Performance and Outlook 2026,” September 2026.
  7. FAA. “Commercial Aviation Forecast FY2026–2046,” 2026.
  8. McKinsey & Company. “The Next Era of Defense Technology Investments,” 2026.
  9. Deloitte. “2026 Aerospace and Defense Industry Outlook,” 2026.
  10. PwC. “Aerospace and Defense Deals Insights: Mid-Year 2026 Review,” 2026.
  11. Reuters. “Defense Spending Priorities Continue to Focus on Missiles, Autonomous Systems, and Space Capabilities,” July–August 2026.
  12. Reuters. “Commercial Aerospace Supply Chain Constraints Extend Aircraft Production Backlogs,” August 2026.
  13. Capital IQ. “PCE Transaction Data (Accessed October 2026): Deal Counts, Buyer Mix, State Activity, Transaction Values, and Valuation Metrics.”
  14. Space Foundation. “The Space Report 2026 Q3 Update,” 2026.
  15. National Defense Magazine. “Autonomous Systems, AI, and Missile Defense Remain Top Pentagon Investment Priorities,” September 2026.

Largest Transactions Closed

  • Target
  • Buyer
  • Value($mm)


Source S&P Capital IQ as of 1/17/2025 and PCE Proprietary Data

PCE Transactions

Contacts

David Jasmund

Orlando Office

407-621-2111 |

Read More

Michael Poole

Orlando Office

407-621-2112 |

Read More

Will Stewart

Orlando Office

407-621-2124 |

Read More

Data Assumptions

This report represents transaction activity as mergers & acquisitions, consolidations, restructurings and spin-offs. Targets are defined as U.S. Based companies with either foreign or U.S. based buyers. Transaction information provided is based on closed dates only.

Glossary

EBIT - Earnings Before Interest and Taxes
EBITDA - Earnings Before Interest, Taxes, Depreciation, Amortization
LTM - Last Twelve Months
TEV - Total Enterprise Value

Sources:

  1. 1. Economic Research Service. “Summary Findings.” U.S. Department of Agriculture, 20, December, 2024
  2. 2. Sarah, Z. “Farm bill extended in last minute funding deal: What to know.” Agriculture Dive, 21, December, 2024
  3. 3. TreeHouse Foods, Inc. Announces Acquisition of Private Brands Category Leader Harris Tea.” TreeHouse Foods, Inc, 2, December, 2024
  4. 4. Christopher, D. “Food and beverage M&A activity appears to be picking up, CoBank says.” Agriculture Dive, 5, November, 2025
  5. 5. Peyton, B. “Grocery e-commerce sales continue to soar.” Grocery Dive, 11, December, 2024