Nicole Kiriakopoulos

E: nicolek@pcecompanies.com

Follow me: LinkedIn

Executive Summary


M&A activity in Building Products & Construction strengthened in Q3 2026, with 814 transactions closed over the trailing 12 months—up 3.2% from Q3 2025. Strategic acquirers drove 701 transactions, or 89.3% of disclosed buyer activity, while financial buyers accounted for 84 deals. Valuations moderated but remained healthy, with median TEV/EBITDA at 11.2x and TEV/Revenue at 1.61x. Large-scale consolidation was led by QXO’s $17.4B acquisition of TopBuild, Martin Marietta’s $13.7B purchase of Lhoist North America, and Berkshire Hathaway’s $9.2B acquisition of Taylor Morrison.

Data center construction remains the sector’s standout growth engine, with spending reaching an estimated $85.0B annualized rate in August 2026, more than 73% above the prior year even as power and permitting constraints delay some projects. Buyers continue to pay for data center-linked capabilities; however, buyer appetite has become more selective, and sellers with heavy data center concentration can be harder to market than they were a year ago as diligence increasingly focuses on customer concentration, power availability, permitting, and backlog durability.7 8 9 10 14
 Get the latest industry insights. 

“Building products and construction M&A maintained its momentum in Q3, as strategic buyers continued to pursue larger platforms with strong backlogs, exposure to infrastructure spending and differentiated capabilities,” said Nicole Kiriakopoulos, Director at PCE. “Despite ongoing labor, cost and interest-rate pressures, healthy valuation multiples and continued activity across specialty services and building products show that buyers remain willing to pay for high-quality assets.”

Market Dynamics


Deal activity improved despite a softer construction backdrop, with buyers prioritizing scale, labor capacity, infrastructure exposure, and specialty service density. U.S. Census Bureau data showed July 2026 construction spending down 3.8% year over year, while the NAHB/Wells Fargo Housing Market Index fell to 32 in September amid higher rates, material costs, and labor constraints. Homebuilding M&A has remained active: the share of builders reporting increased acquisition activity in their local markets rose from 14% in August 2025 to 21% in June 2026, and the share approached about a potential sale or merger doubled from 9% to 18%.

Buyer interest is strongest in fast-growing U.S. markets where an acquisition can add entitled land, local operating teams, purchasing scale, and geographic density. Acquirers are chasing scaled regional homebuilders and specialty construction businesses with defensible local positions, skilled labor, backlogs, recurring service demand, and clear add-on potential; activity has been strong across HVAC, electrical, roofing, plumbing, and specialty trades.

The residential and commercial markets are not moving in lockstep: residential-facing businesses remain more exposed to mortgage rates and affordability pressure, while commercial and industrial demand is stronger in data centers, power, utilities, and other mission-critical infrastructure, with softer conditions in portions of traditional commercial construction. Valuations eased from Q3 2025 but remained resilient as acquirers continued to pursue platforms tied to utilities, infrastructure services, specialty building products, and homebuilding. Large strategic transactions drove disclosed value, while smaller add-ons remained active across electrical, HVAC, roofing, testing, paving, and engineering services.1 2 5 11 12
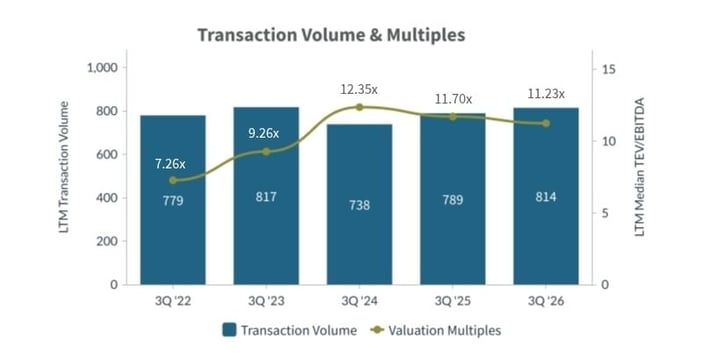
Q3-2026-Transaction Volume and Multiples Building Products Construction Industry

Buyer Landscape


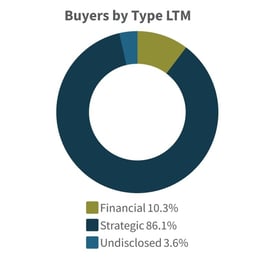
Q3-2026-Buyers by Type LTM Building Products Construction Industry

Strategic Acquirers: Strategics completed 701 of 814 LTM transactions (89.3%), targeting scaled platforms in homebuilding, construction materials, infrastructure services, electrical contracting, and specialty building products. The largest transactions reflected demand for category leaders with national reach, project backlog visibility, and opportunities for vertical integration.5

Financial Buyers: Financial buyers completed 84 transactions (10.7%), with activity concentrated in fragmented niches where sponsor-backed platforms can add density through bolt-ons. Q3 examples included garage doors, modular systems, cabling, engineering, and pool services, underscoring continued interest in recurring service demand and specialty contractor consolidation.
Industry Comparison


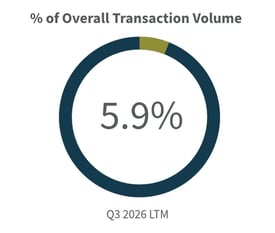
Q3-2026-Overall Transaction Volume Building Products Construction Industry

Building Products & Construction accounted for 6.6% of all U.S. M&A in Q3 2026 and 5.9% on an LTM basis, modestly ahead of its Q3 2025 quarterly share. Sector activity remained durable despite a lower overall transaction market, supported by infrastructure-linked work, homebuilding consolidation, and strategic demand for scaled specialty platforms.


Geographic Expansion


Top U.S. States: Texas (91), Florida (85), and California (78) led LTM transaction activity in Q3 2026, reflecting continued M&A concentration in large, high-growth construction markets.

Featured State Activity: Florida remained especially active, supported by homebuilding, infrastructure, utilities, and specialty contractor transactions, while Texas continued to benefit from construction materials, power, paving, and industrial services activity.
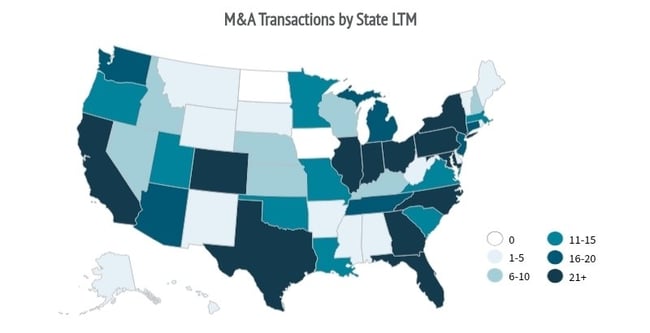
Q3-2026-MA Transactions by State Building Products Construction Industry

Notable Transactions


Largest Transactions Closed

Target Buyer Value ($mm)
TopBuild Corp. QXO, Inc. $17,423.36
Lhoist North America, Inc. Martin Marietta Materials, Inc. $13,748.04
Taylor Morrison Home Corporation Berkshire Hathaway Inc. $9,237.63
Traverse Midstream Partners LLC ePointZero Holding RSC Ltd $2,250.00
Electrical Specialists, Inc. MasTec, Inc. $1,630.13
JFB Construction Holdings Xtend AI Robotics, Inc. $1,500.00
Maritime Applied Physics Corporation AEVEX Corp. $581.91
Associated Steel Group, LLC Development Bank of Japan Inc.; Hanwa American Corp. $347.00
Valley Holdings I, Inc. MYR Group Inc. $328.00
National Technology Integrators, LLC Dycom Industries, Inc. $275.00

Other Financial Buyer Transactions Closed

Target Buyer Value ($mm)
Safe-Way Garage Doors LLC. Point 41 Capital Partners, L.P. n/a
STARC Systems, Inc. Bertram Capital Management, LLC n/a
Performance Cabling Technologies, Inc. Evolution Strategy Partners n/a
CTA Inc. CIVC Partners, L.P. n/a
Shasta Pools & Spas, Inc. Accrual Equity Partners; Dansons Capital Group; Hydro Construction, LLC n/a

Other Strategic Buyer Transactions Closed

Target Buyer Value ($mm)
Kalwall Corporation Apogee Enterprises, Inc. $115.00
Ellsworth Construction, LLC Construction Partners, Inc. $112.00
Roberson Waite Electric SOLV Energy, Inc. $45.00
ValCor Communications, LLC Southern Maryland Cable, Inc. $8.30
Plant Engineering Services Inc. Cemtrex, Inc. $5.25

Source S&P Capital IQ as of 10/1/2026 and PCE Proprietary Data

Emerging Trends


Key trends shaping Building Products and Construction M&A:

  1. Energy Efficiency & Codes
    Tighter building codes and rebate programs are sustaining demand for energy-efficient products. Despite speculation that the new administration may ease off green initiatives, key incentives and tax credits remain in place, keeping buyers focused on companies whose products qualify.
  2. Data Center Construction
    Data centers are now the main growth driver in U.S. nonresidential construction: ABC calculates that data center spending has grown at a 149% annualized pace since March, while AGC reports 55% of contractors saw projects canceled, postponed, or scaled back recently, often due to cost. Activity is not on pause, but it is increasingly constrained: Texas froze new data center grid approvals in August and state-issued permits in September, putting up to ~50 GW of the U.S. pipeline at risk, and transformer and switchgear lead times remain a bottleneck. Investment is still flowing, with Amazon guiding to ~$220B of 2026 capex and debt and infrastructure capital funding power and campus buildouts. For M&A, data center and power exposure has supported higher multiples and private equity interest in electrical, mechanical, and building products platforms. That said, buyer appetite has become increasingly selective: companies with concentrated data center exposure—particularly reliance on a small number of hyperscale customers or projects—can now be harder to market as buyers pressure-test customer concentration, backlog durability, power availability, permitting, and execution risk. This represents a relatively recent shift from the broad premium these assets commanded a year ago, consistent with 2026 market commentary that appetite remains strong but increasingly selective amid power and AI-related risks.7 8 9 10
  3. Digital Tools & Automation to Offset Labor & Cost Pressures
    With labor shortages and wage growth squeezing margins, firms are leaning into digital tools (estimators, scheduling software, building information modeling) and automation to boost efficiency, reduce rework, and manage complexity. Some firms are also using offshore or nearshore teams for remotely delivered functions such as estimating, BIM production, drafting, project coordination, accounting, procurement support, and other back-office work, allowing scarce domestic staff to focus on project management and field execution. The opportunity is more limited for on-site construction activities, where licensing requirements, local coordination, and physical labor constrain offshoring. Together, technology adoption and selective offshoring can improve scalability and margins, making operating efficiency an increasingly important part of the value proposition.3 13
  4. Building Products Distribution Under Pressure
    Distributors face rising expectations from contractors and digital platforms. The focus is on faster delivery, online ordering, and value-added services like jobsite logistics and customization.
  5. Subsector Spotlight: Modular & Prefabricated Construction
    The market for modular & prefab construction is growing fast—valued at about USD $173.5B in 2025, and projected to reach ~$302B by 2035 (≈ 5.7% CAGR).6
  6. Subsector Spotlight: Roofing Consolidation Trend
    Tariffs, workforce shortages, and rapid tech adoption are reshaping the roofing industry. Contractors and distributors are consolidating to gain scale, secure talent, and invest in digital tools to strengthen resilience and position businesses for premium valuations.

Outlook for Next Quarter


Opportunities: Opportunities remain strongest for scaled platforms tied to infrastructure, utility services, specialty building products, and high-growth Sun Belt markets. Strategic buyers are likely to continue prioritizing assets that add labor capacity, regional density, recurring service demand, or product adjacency.

Risks: Margins may remain pressured by labor availability, wage inflation, interest rates, and raw-material volatility. Companies with limited pricing power or exposure to slower project starts could face more scrutiny from buyers. Contractors and suppliers with concentrated data center exposure may also see added scrutiny if power, permitting, or financing constraints delay large projects.

Predicted Activity: Deal activity is expected to remain active but selective, with strategics continuing to lead volume and sponsors focusing on add-on opportunities in fragmented niches. Larger transactions should continue to favor assets with scale, backlog visibility, and infrastructure or essential-service exposure.4

PCE Transactions


A-1

Served as advisor to A-1 Global as they transferred an interest to A-1 Global ESOP Trust

Beam Team

Served as advisor to The Beam Team on their sale to BDS Solutions Group

Modern Plumbing


Served as advisor to Modern Plumbing Industries as they became 100% ESOP owned

Dellinger


Served as advisor to the trustee of the Dellinger ESOP

Premier Design

Served as advisor to the trustee of the Argent ESOP

Simpson


Served as advisor to Simpson Air on their sale to Del-Air

Ally

Served as advisor to Ally Building Solutions on their sale to Astara Capital Partners

Clune

Served as advisor to Clune Construction Company on their sale to the Clune Construction Company ESOP Trust

Midwest Drywall

Served as advisor to Midwest Drywall Co., Inc. as they became 100% ESOP Owned

Del-Air

Served as advisor to Del-Air on their $45 million debt financing

CMI

Served as advisor to Consolidated Minerals, Inc. on their sale to the CMI ESOP Trust

MMC

Served as advisor to MMC Corp on their acquisition of Building Central Services, Inc.

Williams Electric

Served as advisor to Williams Electric Co., Inc. on their sale to Parsons

Energy Air

Served as advisor to Energy Air, Inc. on their sale to the Energy Air, Inc. ESOP Trust

ABS
Served as advisor to American Builders Supply, Inc. on their acquisition by Bluewolf Capital Partners, LLC
Tri City

Served as advisor to Tri-City Electrical Contractors as they transferred an interest to Tri-City ESOP Trust


Contact Us


Kiriakopoulos 600x600

Nicole Kiriakopoulos
Chicago Office
224-520-1068 |
Email me now

READ MORE →

poole_michael-667x667-1

Michael Poole
Orlando Office
407-621-2112 |
Email me now

READ MORE →


Data Assumptions

This report represents transaction activity as mergers & acquisitions, consolidations, restructurings and spin-offs. Targets are defined as U.S. Based companies with either foreign or U.S. based buyers. Transaction information provided is based on closed dates only.

Glossary

EBIT - Earnings Before Interest and Taxes
EBITDA - Earnings Before Interest, Taxes, Depreciation, Amortization
LTM - Last Twelve Months
TEV - Total Enterprise Value

Sources:

  1. U.S. Census Bureau. “Monthly Construction Spending, July 2026,” U.S. Census Bureau, 1 September 2026.
  2. National Association of Home Builders. “Builder Sentiment Falls on Higher Interest Rates and Costs,” National Association of Home Builders, 16 September 2026.
  3. Associated General Contractors of America and NCCER. “2026 Workforce Survey,” Associated General Contractors of America and NCCER, 3 September 2026.
  4. Associated Builders and Contractors. “ABC Survey: 1 in 6 Members Perform Data Center Work; Backlog Rebounds in August,” Associated Builders and Contractors, 15 September 2026.
  5. FMI. “Building Products M&A and Sector Update: August 2026,” FMI, August 2026.
  6. Future Market Insights. “Modular & Prefabricated Construction Market,” Future Market Insights, 12 August 2025.
  7. Engineering News-Record. “Data Center Construction Spending Accelerates at 149% Annualized Pace,” Engineering News-Record, 1 October 2026.
  8. SAVRN. “The Data Center Supply Chain Crisis, 2024–2026,” SAVRN, 18 August 2026.
  9. Capstone Partners. “Building Products Market Update,” Capstone Partners, 30 June 2026.
  10. Financier Worldwide. “Q&A: Data Centre M&A in 2026,” Financier Worldwide, May 2026.
  11. National Association of Home Builders. “Acquisitions Increasing Among Home Builders,” NAHB, 28 July 2026.
  12. Align Business Advisory. “Specialty Construction M&A Is Accelerating in 2026,” 2 September 2026.
  13. Shor. “Construction Labor Shortage 2026: How Contractors Hire Estimators, Drafters, and Coordinators Abroad,” 31 August 2026.
  14. KPMG. “Data Center Construction Leads,” based on U.S. Census Bureau August 2026 construction spending data, 2026.

Largest Transactions Closed

  • Target
  • Buyer
  • Value($mm)


Source S&P Capital IQ as of 1/17/2025 and PCE Proprietary Data

PCE Transactions

Contacts

David Jasmund

Orlando Office

407-621-2111 |

Read More

Michael Poole

Orlando Office

407-621-2112 |

Read More

Will Stewart

Orlando Office

407-621-2124 |

Read More

Data Assumptions

This report represents transaction activity as mergers & acquisitions, consolidations, restructurings and spin-offs. Targets are defined as U.S. Based companies with either foreign or U.S. based buyers. Transaction information provided is based on closed dates only.

Glossary

EBIT - Earnings Before Interest and Taxes
EBITDA - Earnings Before Interest, Taxes, Depreciation, Amortization
LTM - Last Twelve Months
TEV - Total Enterprise Value

Sources:

  1. 1. Economic Research Service. “Summary Findings.” U.S. Department of Agriculture, 20, December, 2024
  2. 2. Sarah, Z. “Farm bill extended in last minute funding deal: What to know.” Agriculture Dive, 21, December, 2024
  3. 3. TreeHouse Foods, Inc. Announces Acquisition of Private Brands Category Leader Harris Tea.” TreeHouse Foods, Inc, 2, December, 2024
  4. 4. Christopher, D. “Food and beverage M&A activity appears to be picking up, CoBank says.” Agriculture Dive, 5, November, 2025
  5. 5. Peyton, B. “Grocery e-commerce sales continue to soar.” Grocery Dive, 11, December, 2024