


Industry Trends
Largest Transactions Closed
- Target
- Buyer
- Value($mm)
Advised Western Milling in their sale to the Western Milling ESOP Trust

Last updated:
Buyers favored scaled, resilient industrial businesses in Q3 2026, particularly those benefiting from recurring revenue, infrastructure investment, electrification, and supply-chain localization. Strategic acquirers dominated, while financial buyers remained selective amid elevated financing costs and trade-policy uncertainty. The largest transactions were Baker Hughes’ $14.1 billion acquisition of Chart Industries, Parker-Hannifin’s $9.3 billion acquisition of Filtration Group, and AMETEK’s $5.0 billion acquisition of Indicor’s instrumentation businesses.
“Diversified Industrials M&A activity remained strong, with stable volume and expanding valuations as buyers pursued scaled, resilient businesses,” said Michael Rosendahl, Managing Director at PCE.
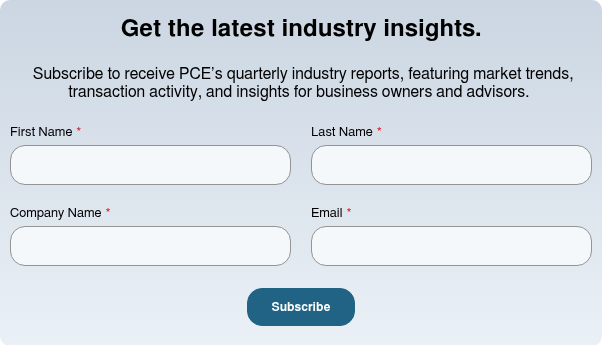
Diversified Industrials M&A totaled 1,438 LTM transactions in Q3 2026, versus 1,428 a year earlier, with 278 quarterly deals. Median EV/EBITDA increased to 13.03x from 12.83x, while median EV/revenue rose to 2.15x from 2.09x. Strategic buyers pursued vertical integration, supply-chain control, and aftermarket capabilities, while financial buyers remained selective amid higher capital costs. Large transactions involving Chart Industries, Filtration Group, and Indicor’s instrumentation businesses concentrated value, with electrification, infrastructure, and specialized manufacturing assets drawing the strongest interest.
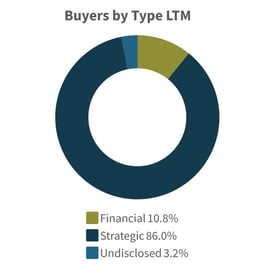
Strategic Acquirers: 1,222 of 1,438 LTM transactions (84.98%), focused on scale, vertical integration, and synergy capture across manufacturing, industrial services, and infrastructure.
Financial Buyers: 154 of 1,438 (10.71%), targeting resilient industrial services, components, and specialized manufacturing businesses.
Undisclosed Buyers: 62 of 1,438 (4.31%), primarily private operators and regional platforms.1
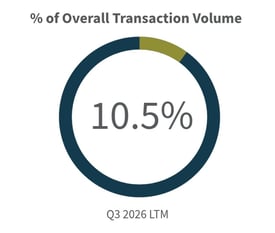
Diversified Industrials represented 12% of overall Q3 U.S. M&A volume and 10.5% of LTM activity. Transaction volume remained broadly stable versus 2025 as valuation multiples expanded, reflecting demand for resilient operations and margin stability. Activity centered on strategic acquisitions of Chart Industries, Filtration Group, and Indicor’s instrumentation businesses, while additional infrastructure and distribution deals reinforced buyer interest in scale, specialization, and recurring revenue. Sponsor activity remained selective, with the $2.0 billion Madison Fire & Rescue transaction the largest disclosed financial-buyer deal in Q3.1
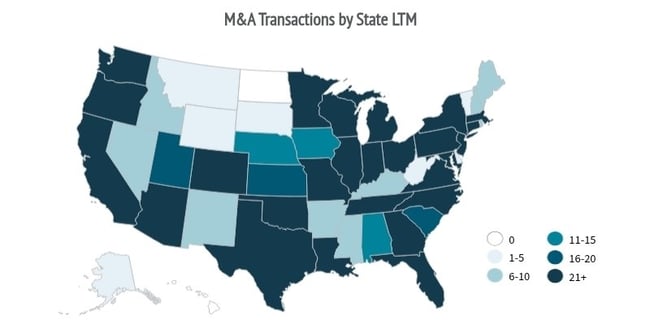
Top U.S. States: Texas (150 deals), California (130), and Florida (117) led Q3 2026 LTM seller activity, followed by Illinois (65) and Ohio (63), reflecting strong industrial investment and favorable operating conditions in major markets.
Regional Breadth: The Sunbelt and Southeast benefited from population growth, lower costs, faster permitting, and available power, while Midwestern states maintained steady manufacturing, machinery, and logistics activity. Elevated manufacturing construction and clean-energy investment continue to support broad geographic demand.
| Target | Buyer | Value |
| Chart Industries, Inc. | Baker Hughes Company | $14,063.31 |
| Filtration Group Corporation | Parker-Hannifin Corporation | $9,250.00 |
| portfolio of instrumentation businesses of Indicor, LLC | AMETEK, Inc. | $5,000.00 |
| Traverse Midstream Partners LLC | ePointZero Holding RSC Ltd | $2,250.00 |
| Madison Fire & Rescue | Bain Capital, LP; 3M Company | $1,950.00 |
| Electrical Specialists, Inc. | MasTec, Inc. | $1,630.13 |
| FloWorks International LLC | Ferguson Enterprises Inc. | $1,600.00 |
| JFB Construction Holdings | Xtend AI Robotics, Inc. | $1,500.00 |
| Maritime Applied Physics Corporation | AEVEX Corp. | $581.91 |
| Southern Parts & Equipment, Inc. | FreightCar America, Inc. | $511.00 |
| Target | Buyer | Value |
| Blastco Texas Inc. | LWO LLC | n/a |
| Next Point Bearing Group, LLC | Pfingsten Partners, L.L.C. | n/a |
| American Piping Products Inc. | SCF Partners, Inc. | n/a |
| Safe-Way Garage Doors LLC. | Point 41 Capital Partners, L.P. | n/a |
| M & N Plastics, Inc. | New Water Capital, L.P. | n/a |
| Target | Buyer | Value |
| CORMETECH, Inc. | Johnson Matthey Plc | $460.00 |
| Valco Cincinnati, Inc. | Graco Inc. | $447.00 |
| Cat Pumps Corporation | Franklin Electric Co., Inc. | $400.00 |
| Prevalon Energy LLC | Nextpower Inc. | $365.00 |
Source S&P Capital IQ as of 10/1/2026 and PCE Proprietary Data
Opportunities: Buyers should continue pursuing manufacturing, industrial distribution, engineering services, grid modernization, and data-center infrastructure offering resilient cash flows and demand visibility.2 7
Risks: Tariffs, input-cost volatility, higher rates, tighter credit, labor shortages, and geopolitical disruption may compress margins, widen valuation gaps, and slow deal pacing.3 6
Predicted Activity: Strategic acquirers should lead bolt-ons and consolidations, while sponsors prioritize specialized, recurring-revenue businesses and cross-border buyers seek U.S. production capacity.2
Michael Rosendahl |
Ken Sommers |
Michael Poole |
Advised Western Milling in their sale to the Western Milling ESOP Trust
