


Industry Trends
Largest Transactions Closed
- Target
- Buyer
- Value($mm)
Advised Western Milling in their sale to the Western Milling ESOP Trust

Last updated:
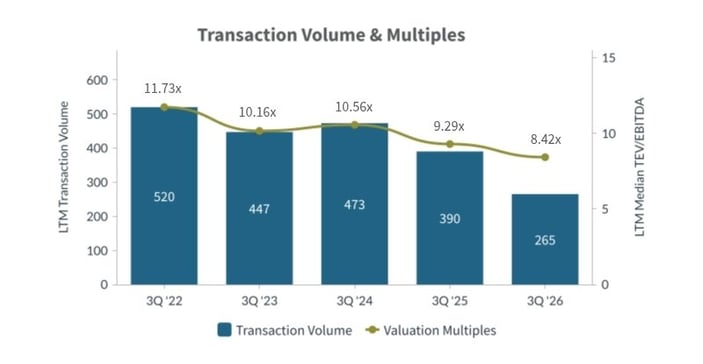
M&A activity in the Food amp; Agriculture sector continued to moderate through Q3 2026, with 265 closed transactions on an LTM basis, down from 390 in Q3 2025 and 473 in Q3 2024. The slowdown reflected ongoing selectivity from buyers, tighter underwriting standards, and continued focus on margin durability across food, beverage, agriculture, and consumer staples platforms.
Quarterly activity totaled 49 closed transactions in Q3 2026, with strategic buyers remaining active in branded foods, beverage, distribution, and specialty processing assets where scale, supply chain control, and category relevance remain important acquisition drivers.
Strategic buyers accounted for approximately 81% of LTM transactions (215 of 265), while financial buyers represented approximately 19% (50 of 265), highlighting continued sponsor selectivity but relatively stronger financial buyer participation compared with the prior-year period.
Valuation multiples compressed further, with median TEV/EBITDA declining to 8.42x and median TEV/Revenue declining to 1.24x, as buyers continued to prioritize quality of earnings, pricing power, and reduced exposure to commodity and input-cost volatility.
Notable Q3 2026 transactions included The Vita Coco Company’s acquisition of Copra Inc., KDSA Investment Partners’ acquisition of Watkins Incorporated, and Vireo Growth’s acquisition of certain PharmaCann retail assets, underscoring buyer interest in scaled beverage, branded food, and consumer staples platforms.1
“We are seeing buyers separate durable food and agriculture platforms from businesses that are more exposed to margin volatility,” said Michael Poole, Managing Director at PCE. “That creates a more disciplined market, but also one where well-positioned companies can still generate meaningful competitive tension.”
Valuation pressure persisted in Q3 2026 as buyers maintained disciplined underwriting and focused on proven profitability. Revenue multiples declined to 1.24x, while EBITDA multiples declined to 8.42x, continuing the multi-year decline from Q3 2024 and Q3 2025 levels.
Buyers remained selective, with the strongest demand centered on assets that demonstrated resilient demand, defensible margins, and operational control. Commodity-exposed businesses and platforms with weaker visibility faced more scrutiny, while differentiated branded, beverage, ingredient, and distribution assets continued to attract interest.1
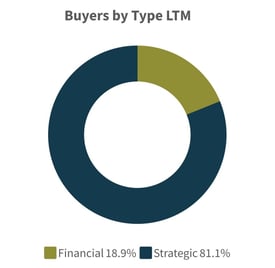
Strategic Acquirers: Strategic buyers dominated activity, accounting for 81% of LTM transactions (215 of 265), with consolidation driven by established food, beverage, agriculture, and consumer staples platforms seeking category expansion, distribution scale, and supply chain control. Notable Q3 transactions included The Vita Coco Company’s acquisition of Copra Inc., Vireo Growth’s acquisition of certain PharmaCann retail assets, and Tradebe Life Sciences’ acquisition of CitraSource Holdings.1
Financial Buyers: Financial buyers represented approximately 19% of LTM deal volume (50 transactions), reflecting continued sponsor selectivity but meaningful participation in durable food and agriculture platforms. Q3 financial buyer activity included acquisitions of Brazi Bites by Midwest Growth Partners, Custom Ingredients by Graham Partners and Butterfly Equity, Lyons Magnus by Truelink Capital Management, National Water Services by TowerBrook Capital Partners, and DecoPac by Sentinel Capital Partners.1
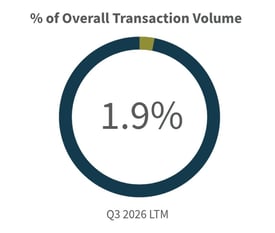
The Food & Agriculture sector continued to trail broader market activity in Q3 2026, with 265 LTM transactions representing approximately 1.9% of overall LTM M&A volume. Relative to the broader market, sector activity remained more selective but continued to benefit from defensive demand characteristics, recurring consumption patterns, and strategic relevance across food production, beverage, distribution, and agriculture supply chains.
Although LTM transaction volume declined from 390 in Q3 2025 to 265 in Q3 2026, strategic buyers remained the primary driver of activity, and valuation discipline was evident across the sector. The market is expected to remain selective, with differentiated platforms better positioned to attract buyer interest than commodity-exposed or margin-volatile businesses.
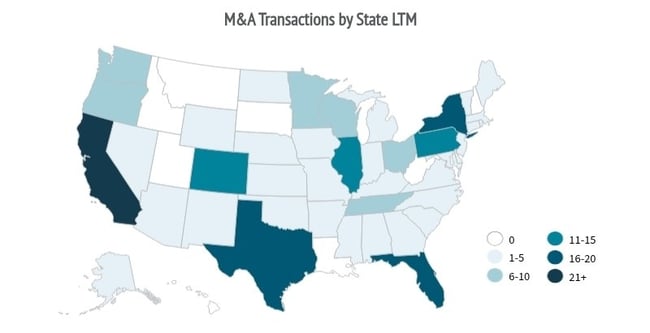
Top U.S. States: California led all states with 49 transactions, followed by New York (19) and Texas (18), underscoring the strength of coastal markets with deep agribusiness networks and food innovation clusters.1
Cross-Border Trends: While U.S.-based targets accounted for most transactions, cross-border participation persisted, led by Canadian and European buyers seeking growth and diversification within U.S. food production, ingredients, and distribution segments.
| Target | Buyer | Value |
| Copra Inc. | The Vita Coco Company, Inc. | $275 |
| Watkins Incorporated | KDSA Investment Partners, LLC | $90 |
| Certain retail assets and properties of PharmaCann Inc. | Vireo Growth Inc. | $49 |
| CitraSource Holdings, L.L.C. | Tradebe Life Sciences | $41 |
| Garrard County Distilling Co. | Tom Collins Distilling LLC | $20 |
| Healthy Choice Wellness Corp. | Host Digital Inc. | $13 |
| Custom Foods Inc. | Starco Manufacturing, LLC | $11 |
| XYZ Beverage LLC | Go 4 It Beverage, LLC | $1 |
| Pacific Rim and Company | WarRoom Ventures, LLC | n/a |
| Target | Buyer | Value |
| Fiore Di Pasta, Inc. | Turri's Italian Foods, Inc. | n/a |
| Beach Cooperative Grain Company | The Arthur Companies, Inc. | n/a |
| Lewis Bamboo, Inc. | Patten Seed Holdings, LLC | n/a |
| Family Tree Produce, Inc. | Loewy Enterprises, LLC | n/a |
| Epicurean Butter Holdco, Inc. | Solina Group Holding | n/a |
| Target | Buyer | Value |
| Brazi Bites, LLC | Midwest Growth Partners, LLLP | n/a |
| Custom Ingredients, Inc | Graham Partners, LLC; Butterfly Equity, LP | n/a |
| Lyons Magnus, LLC | Truelink Capital Management, LLC | n/a |
| National Water Services, Inc. | TowerBrook Capital Partners L.P. | n/a |
| DecoPac, Inc. | Sentinel Capital Partners, L.L.C. | n/a |
Source S&P Capital IQ as of 10/1/2026 and PCE Proprietary Data
Opportunities: Buyer interest should favor technology-enabled processors, traceability solutions and differentiated nutrition platforms that can improve productivity or sustain premium pricing.4 5
Risks: Higher farm inputs and persistent foodservice inflation may compress margins and widen valuation gaps for commodity-exposed or labor-intensive businesses.2 3
Predicted Activity: Q4 activity is expected to remain selective, with strategic buyers prioritizing resilient cash flow, supply-chain control and clear operational synergies.
David Jasmund |
Michael Poole |
|
Advised Western Milling in their sale to the Western Milling ESOP Trust
