




Industry Trends
Largest Transactions Closed
- Target
- Buyer
- Value($mm)
Advised Western Milling in their sale to the Western Milling ESOP Trust

Last updated:
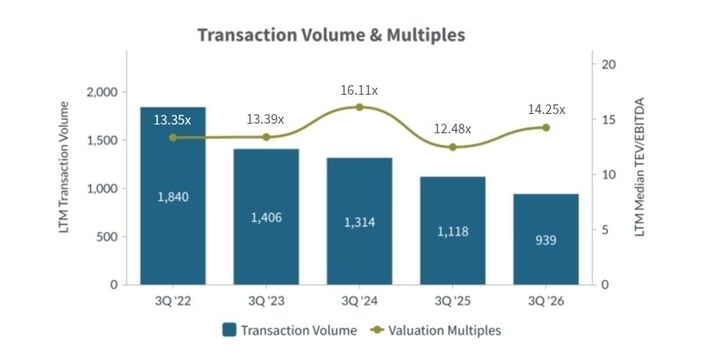
Healthcare M&A remained strategically resilient through Q3 2026 despite a meaningful decline in deal volume. Valuations strengthened to median multiples of 14.25x TEV/EBITDA and 3.77x TEV/Revenue, while strategic buyers drove 838 transactions, or 89.2% of LTM activity. Overall, 939 transactions closed during the last twelve months, down 16.0% from 1,118 in the prior-year period; financial buyers completed 101 deals. Healthcare also represented 7.2% of Q3 transaction volume, compared with 6.9% on an LTM basis, signaling sustained buyer demand in a more selective market.1
“Operational strength is becoming the key differentiator for healthcare businesses as buyers weigh rising labor costs, reimbursement pressure, and affordability concerns,” said Bradley Scharfenberg, Vice President at PCE. “Companies with efficient staffing, durable margins, and a clear value proposition for patients and providers will be best positioned to stand out.”
Q3 accounted for 162 healthcare transactions, representing approximately 17% of the 939 healthcare deals completed during the LTM period. Quarterly activity therefore remained below the average for the trailing twelve months, pointing to continued near-term softness rather than a broad-based rebound in transaction volume.
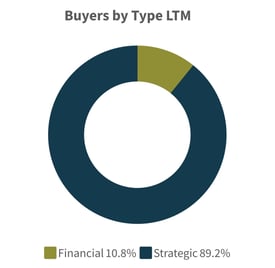
Strategic Acquirers: Strategic buyers dominated Q3 2026 activity, representing 838 deals (89.2%) in the LTM period. The largest announced outcomes reflected continued demand for therapeutics and specialty healthcare assets, led by AbbVie’s $10.7B acquisition of Apogee Therapeutics, GlaxoSmithKline’s $10.6B acquisition of Nuvalent, and Vertex Pharmaceuticals’ $8.9B acquisition of Crinetics Pharmaceuticals.1
Financial Buyers: Financial sponsors accounted for 101 deals (10.8%) in the LTM period. Representative Q3 2026 transactions included Montagu Private Equity and Kohlberg & Company’s $1.5B acquisition of Telex Medical OEM, AIP’s $1.3B acquisition of Arams Medical, and Astorg’s $1.1B acquisition of Thermo Fisher Scientific’s global microbiology business.1
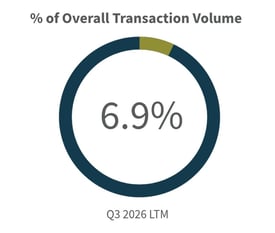
Healthcare transaction activity remained comparatively resilient within the broader M&A market. The sector represented 7.2% of all Q3 2026 transactions, above its 6.9% share of LTM volume, indicating that healthcare captured a modestly larger portion of deal activity during the quarter despite lower absolute transaction volume. The increase in relative share suggests sector demand held up better than the headline volume decline across industries.
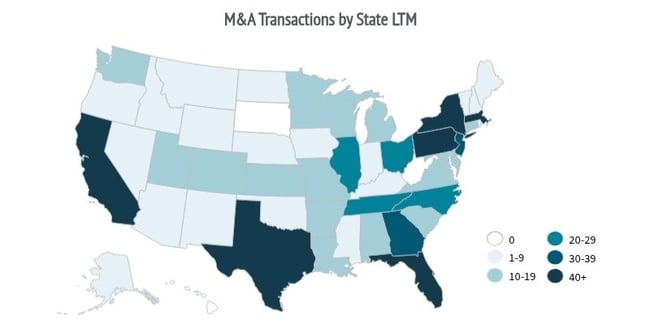
Top U.S. States: Deal flow remained geographically diversified across major healthcare and life sciences hubs. California led all states with 138 transactions, followed by Florida (88), Texas (70), Massachusetts (53), and New York (52).1
Cross-Border Trends: Cross-border M&A activity in Q3 2025 was driven by major European acquirers such as Sanofi, Merck KGaA, and GSK, which pursued U.S. biotech and therapeutic assets to expand global pipelines and strengthen specialty drug portfolios.
| Target | Buyer | Value ($mm) |
| Apogee Therapeutics, Inc. | AbbVie Inc. | $10,695 |
| Nuvalent, Inc. | GlaxoSmithKline LLC | $10,629 |
| Crinetics Pharmaceuticals, Inc. | Vertex Pharmaceuticals Incorporated | $8,866 |
| Catalyst Pharmaceuticals, Inc. | Angelini Pharma S.p.a. | $4,100 |
| AtaiBeckley Inc. | Eli Lilly and Company | $3,722 |
| Sevasemten and Muscular Dystrophy Business of Edgewise Therapeutics, Inc | Servier Pharmaceuticals LLC | $2,650 |
| Forte Biosciences, Inc. | argenx SE | $2,118 |
| Vega Therapeutics, Inc. | Incyte Corporation | $2,000 |
| Kartos Therapeutics, Inc. | Ipsen S.A. | $1,750 |
| Esperion Therapeutics, Inc. | ArchiMed SAS | $1,543 |
| Target | Buyer | Value ($mm) |
| Teleflex Medical OEM LLC | Montagu Private Equity LLP; Kohlberg & Company, L.L.C. | $1,500 |
| Avanos Medical, Inc. | AIP, LLC | $1,397 |
| Global Microbiology Business of Thermo Fisher Scientific Inc. | Astorg Asset Management S A.R.L. | $1,075 |
| MatrixCare, Inc. | Frazier Management, L.L.C. | $490 |
| Cross Country Healthcare, Inc. | Knox Lane LP | $439 |
| Target | Buyer | Value ($mm) |
| Riverpoint Medical, LLC | Novanta Inc. | $1,450 |
| Actio Biosciences, Inc. | Jazz Pharmaceuticals plc | $1,320 |
| Kashiv BioSciences, LLC | Amneal Pharmaceuticals, Inc. | $1,102 |
| XOMA Royalty Corporation | Ligand Pharmaceuticals Incorporated | $1,049 |
| RayThera Inc. | Biogen Inc. | $1,000 |
Source S&P Capital IQ as of 10/1/2026 and PCE Proprietary Data
Opportunities: Q4 2026 interest should favor AI-enabled workflow tools, scalable outpatient models, and medtech platforms that expand procedural capacity while demonstrating clear clinical and financial ROI.2 4
Risks: Wage and benefit inflation, reimbursement pressure, implementation costs, and heightened scrutiny of provider pricing may temper valuations for labor-intensive or operationally complex assets3 5
Predicted Activity: Activity should remain selective but steady, led by strategic tuck-ins and sponsor-backed platforms with defensible specialties, recurring revenue, and credible technology-enabled margin expansion.
David Jasmund |
Jon Gogolak |
Bradley Scharfenberg |
Advised Western Milling in their sale to the Western Milling ESOP Trust
